

CoverMe - Instant Cash Advance

- 2.10K Reviews
- 4.6
- Downloads
- 100,000+
Our take on CoverMe - Instant Cash Advance from Appgk
I approached CoverMe as a practical finance app rather than something to browse for entertainment. Its promise is straightforward: help bridge a cash gap when the next payday is still far away. That makes the first impression easy to understand, but the real question is more important: does it remain useful after the immediate emergency has passed, or does it become another app that only feels valuable when money is tight?
My answer is cautious but positive. CoverMe can be useful for a specific kind of short-term cash problem, especially when an unexpected expense cannot wait. At the same time, I would not treat it as a replacement for budgeting, savings, or a normal bank account. The app’s strongest role is as a narrowly focused financial tool, not as a complete money-management system.
How CoverMe fits into real financial life
CoverMe is a free finance app from DIONIS K, with an Everyone content rating and support beginning with Android 7.0. It was released on February 20, 2025, and the current version is 1.6.3. The app has built a visible audience, with a 4.6 average from around 32 thousand ratings and more than 100 thousand installs. Those figures suggest that the idea is connecting with people, although popularity alone does not tell me whether the service will suit a particular financial situation.
The central appeal is timing. A normal payday advance is usually associated with a much shorter wait, while CoverMe presents itself for people whose next payday may be as far away as 96 weeks. That makes the app sound less like a conventional emergency bridge and more like an option for users who need access to cash without relying on the usual payday schedule.
Best Parts of CoverMe - Instant Cash Advance
Things to Keep in Mind About CoverMe - Instant Cash Advance
That distinction matters. If I only needed a small amount for a bill due tomorrow, I would first look at money already available to me, a conventional bank transfer, or a clearly understood credit option. CoverMe becomes more interesting when the problem is not simply “I need money today,” but “my income timing does not line up with a necessary expense.” The longer time horizon may be the reason someone considers it in the first place.
The first-week appeal is mostly about clarity
During an initial trial of any cash-advance app, I pay attention to how quickly the purpose becomes clear. CoverMe benefits from having a focused identity. I do not have to sort through investing tools, spending charts, bill calendars, or unrelated financial features before understanding why I might open it. Its place in the finance category is obvious: it is aimed at access to cash when ordinary timing is inconvenient.
News and Features Related to CoverMe - Instant Cash Advance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
That focus is useful for a person who is already under pressure. When a car repair, utility bill, medical purchase, or urgent household expense appears, a complicated interface can make a stressful situation worse. A focused app can reduce the number of decisions I need to make before deciding whether it is worth continuing.
Still, simplicity at the front does not automatically mean simplicity at the end. Cash-related products deserve slower reading than a typical utility app. I would examine the full repayment structure, eligibility conditions, transfer timing, and any cost attached to receiving or repaying funds before accepting anything. A clean first screen should never replace careful financial judgment.
Don't want to read the full review?
One practical habit makes the first week safer: I would use CoverMe only after writing down the exact expense, the amount required, and the date on which repayment would be realistic. That small step prevents the app from turning a defined shortfall into an open-ended request. It also shows whether I need the full amount or only a smaller bridge.
A realistic emergency scenario
Imagine that I receive an unexpected repair bill shortly after paying rent, while my next reliable income is not arriving soon. I could open CoverMe to explore whether its cash-advance approach fits the situation. Before proceeding, I would compare the amount I need with what I can repay without sacrificing food, housing, transport, or other essentials.
Screenshots
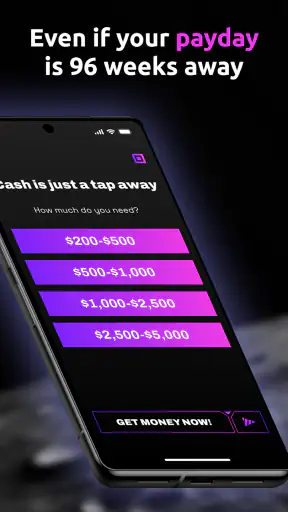
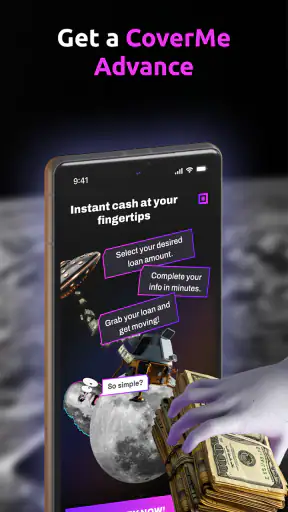
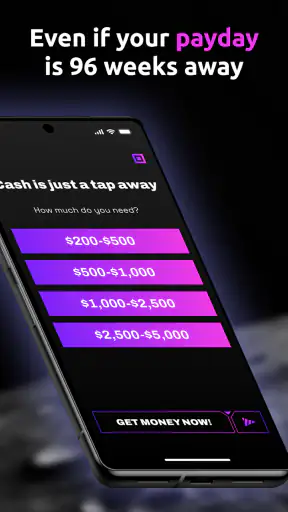
If the repair is necessary and the repayment plan is genuinely manageable, the app may provide a useful route to handle the immediate problem. If repayment would simply create another crisis a few weeks later, the advance would only move the pressure forward. That is the most important trade-off: access to cash can solve a timing problem, but it cannot solve an income problem by itself.
I would also avoid borrowing extra money just because the available amount is higher than the bill. The safest use is tied to a specific need. CoverMe is easier to judge when I treat it like a precise tool rather than spare spending money.
What becomes valuable month after month
The lasting value of CoverMe depends on whether my financial needs repeatedly involve the same timing problem. Someone paid irregularly, waiting for a delayed contract payment, or dealing with seasonal income may find a cash-access tool more relevant than someone with stable pay and an emergency fund. In those cases, the app’s usefulness comes from flexibility around timing rather than from daily engagement.
That also means I would not expect to open it every day. Unlike a budgeting app, CoverMe does not need to become a constant habit to be useful. Its recurring value may be occasional and situational: I remember it when a legitimate gap appears, review the terms, and decide whether using it is preferable to the alternatives available at that moment.
This is a strength and a weakness. The app can earn a place on my phone without demanding regular tracking, but it may feel unnecessary for long stretches. If my income and expenses are predictable, a savings buffer is usually more valuable over time because it avoids creating a repayment obligation. CoverMe is most relevant when predictability is missing or when building savings has not yet been possible.
For month-to-month use, I would create a simple personal rule: never use a new advance to repay an earlier one. That rule is more important than any convenience the app offers. Repeated borrowing can make a short-term tool feel like a permanent part of the budget, which is exactly when its practical value starts to decline.
How it compares with familiar alternatives
Compared with a standard payday advance, CoverMe’s stated long-range timing is its clearest point of difference. A conventional payday product is generally built around the next pay cycle, while this app is positioned for people who may be waiting much longer. That could make it more relevant when a user’s income is delayed rather than merely a few days away.
Compared with a credit card, the decision is less about convenience and more about transparency. A credit card may already be available and familiar, but its balance can remain open and easy to carry forward. With a cash-advance app, I would want to understand the repayment expectations before accepting money. Neither option is automatically better; the right choice depends on the cost, timing, and certainty of repayment.
Compared with an overdraft, CoverMe may appeal to someone who wants to avoid pushing a bank account below zero. However, avoiding an overdraft does not make borrowing free or risk-free. I would compare the total obligation, the repayment date, and the consequences of being late rather than choosing based on the label alone.
Compared with a savings app, CoverMe serves the opposite moment. Savings tools help prevent future shortages, whereas this app is designed for an existing gap. I would use savings whenever I have time to prepare and consider CoverMe only when preparation has failed or the expense could not reasonably have been predicted.
The maintenance burden is low, but the financial discipline is not
CoverMe does not appear to demand the kind of daily maintenance associated with expense trackers or investment dashboards. I would not install it expecting charts, long-term planning, or a complete view of my finances. Its maintenance burden is more personal: I need to remember what I owe, when I owe it, and whether the original reason for borrowing still makes sense.
That creates an important hidden cost in attention. A user might think the app is easy because requesting money is simpler than building a budget. In reality, the difficult work happens outside the interface. I would keep a separate note showing the amount received, the expected repayment date, and the money reserved for repayment. Relying on memory is a poor strategy when finances are already stretched.
I would also review the app before every new use instead of assuming that a previous experience automatically applies. The current version is 1.6.3, but software updates do not remove the need to read the terms attached to a particular transaction. A familiar screen can encourage rushed decisions, so I would slow down precisely when the process feels routine.
Another useful maintenance habit is removing the app from my regular spending mindset. I would not count an available advance as income, include it in my monthly spending allowance, or use it to justify purchases that can wait. Keeping that mental separation protects the app’s limited purpose.
Where user fatigue can appear
The first source of fatigue is uncertainty. People looking for emergency cash often want an immediate answer, but financial products can involve eligibility checks, waiting, repayment details, or conditions that are easy to overlook when someone is worried. If the process feels slower or more conditional than expected, the initial appeal may fade quickly.
The second is repeated decision-making. Every use requires me to ask whether the expense is essential, whether the amount is correct, and whether repayment is realistic. Those questions are healthy, but they also make the app less attractive for casual use. In my view, that is a good kind of friction. A cash tool should not feel as effortless as ordering something online.
The third is emotional fatigue. Borrowing can provide relief at the moment money arrives, followed by anxiety when repayment approaches. CoverMe may reduce the immediate pressure without reducing the underlying stress. Anyone who already feels overwhelmed by debt should be especially careful about adding another obligation, even when the app’s presentation feels approachable.
There is also a risk of confusing long repayment timing with affordability. The fact that an app is designed for a payday that may be far away does not mean a longer timeline is automatically comfortable. A longer period can make a payment seem smaller while keeping the obligation present for much longer. I would judge the complete repayment burden, not just the first amount shown.
Who will get the most from it
CoverMe makes the most sense for an adult who has a specific, urgent expense and a credible plan for repayment. It may also suit someone whose income schedule does not match the short cycle assumed by ordinary payday products. The app’s free download and Everyone rating make it easy to consider, but those points should not be mistaken for a guarantee that borrowing will be suitable.
I would be more comfortable recommending it to a user who has already listed the expense and knows where repayment money will come from. That source might be a confirmed incoming payment, a scheduled work payment, or another dependable event. The key is certainty, not optimism.
I would advise a different route for someone who needs money for discretionary shopping, recurring bills they cannot cover month after month, or an earlier advance. In those situations, a conversation with the bill provider, a spending reduction plan, community assistance, a bank option, or professional debt advice may be more appropriate. The app should not become a substitute for addressing a persistent shortfall.
Who should probably skip it
I would skip CoverMe if I could cover the expense by waiting, using existing savings, or rearranging a nonessential purchase. I would also avoid it if I could not explain exactly how repayment would happen. That may sound obvious, but urgency makes vague plans feel more reliable than they are.
People who want a complete personal-finance dashboard should look elsewhere. CoverMe is not the app I would choose for tracking categories, setting savings goals, reviewing subscriptions, or understanding spending patterns. A budgeting tool is better for preventing the same emergency from repeating.
I would also be cautious if I were already juggling several balances. Adding one more financial commitment can make the overall picture harder to manage, even if the individual amount seems small. In that situation, the app’s convenience may be outweighed by the need for a broader repayment strategy.
Small habits that make use more responsible
My first tip is to calculate the smallest amount that solves the problem. Borrowing exactly what is needed reduces the chance that a temporary advance becomes extra spending room. I would write the bill total down before opening the app and avoid increasing the request simply because a larger amount is available.
My second tip is to schedule repayment mentally before accepting anything. If I cannot point to the income or savings that will cover it, I would stop and reconsider. This turns the app from an impulse response into a deliberate decision.
My third tip is to compare the app with at least one non-borrowing option. That might mean asking for a payment extension, delaying a purchase, selling an unused item, or checking whether a bank account already offers a less costly solution. The comparison does not need to take long, but it can reveal that the cash gap is negotiable.
My fourth tip is to use it as a signal rather than just a solution. If I need CoverMe repeatedly for groceries, utilities, or transport, the pattern tells me that my monthly plan is no longer working. At that point, the most valuable next step is not another advance; it is finding the recurring source of the shortage.
Does it earn lasting space?
After the novelty fades, CoverMe earns space on my phone only for a particular user: someone who occasionally faces a serious timing mismatch and wants a focused way to explore cash access. Its recurring value is not entertainment, daily engagement, or broad financial management. It is the possibility of having a dedicated option ready when ordinary payday timing does not fit.
That limited role is also why I would not recommend it universally. A savings cushion, a clear budget, or a conventional financial product may serve many people better over the long term. CoverMe is useful when those options do not solve the immediate timing problem, but it should remain a backup rather than become the foundation of a financial routine.
My final judgment is that the app is worth considering, not blindly trusting. I like its narrow purpose and its attention to users who may be waiting much longer than a typical payday cycle. I also think its value depends almost entirely on responsible use, careful reading, and a realistic repayment plan. If you have a defined emergency and dependable repayment money, CoverMe may be a practical option to investigate. If the shortage is ongoing or the repayment plan is uncertain, the better long-term choice is to address the budget itself.
CoverMe - Instant Cash Advance FAQ
What is CoverMe - Instant Cash Advance, and how does it work?
CoverMe - Instant Cash Advance is a financial app designed to help eligible users request short-term cash advances through their mobile device. After creating an account, you typically provide personal and financial information, review any available offer, and choose whether to accept it. Approval, advance amounts, transfer speed, fees, and repayment terms can vary by user and provider.
Who can use CoverMe - Instant Cash Advance?
Eligibility depends on factors such as your age, location, identity verification, income, employment details, banking history, and other information reviewed during the application process. Downloading the app does not guarantee approval. Before applying, check the current availability requirements and make sure the personal details you submit are accurate, since incomplete or inconsistent information may delay verification or prevent you from receiving an offer.
How much does CoverMe cost, and are there any fees?
The cost of using CoverMe depends on the specific offer and the financial service provider involved. Possible charges may include membership costs, service fees, expedited transfer fees, or other borrowing-related expenses. Carefully review the disclosure shown before accepting an advance, including the total repayment amount, due date, and any applicable annual percentage rate or equivalent cost.
How quickly can I receive money through CoverMe?
The app may provide access to funds quickly after approval, but delivery time is not guaranteed and can depend on verification, your bank, weekends, holidays, and the transfer method selected. Standard transfers may take longer than expedited options, which could involve an additional fee. Always confirm the estimated arrival time and final cost before completing the request.
Is CoverMe - Instant Cash Advance safe to use?
CoverMe should be used carefully, as with any app handling sensitive financial and banking information. Download it only from an official app store, review its privacy policy and requested permissions, and avoid sharing account credentials outside the secure application. Most importantly, understand repayment obligations and data-sharing practices before accepting an advance, because missed payments or unexpected charges may create financial difficulties.











